The Part About Card Denials Nobody Tells You
Card denials happen for specific, fixable reasons.
Too many late payments. Score too low. Too much debt. Maybe all three.
But not because of who you are.
Well, to be honest, the frustrating part isn’t the denial itself, it’s not knowing which move actually fixes it.
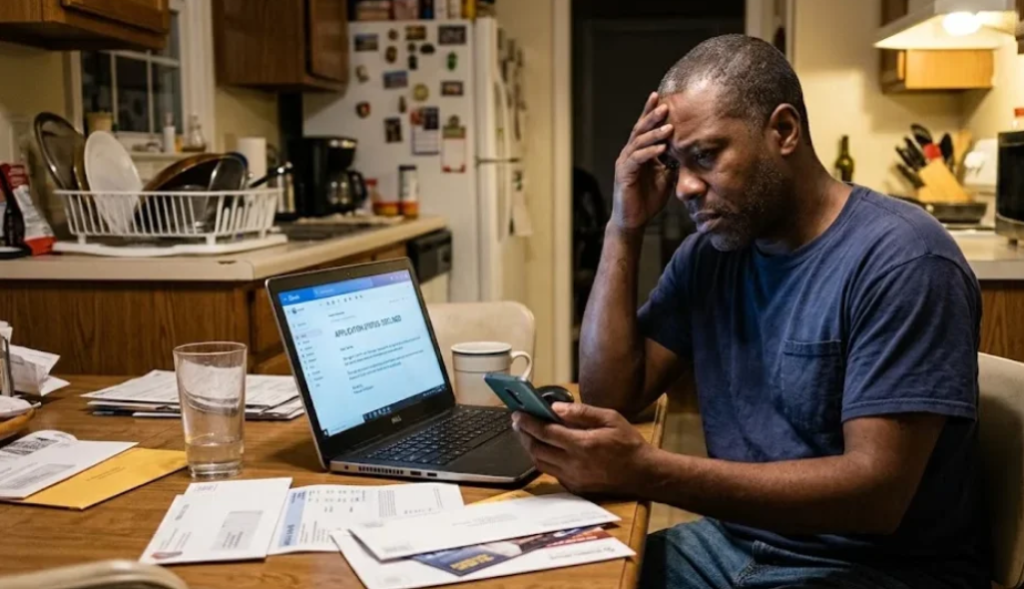
The truth is that you got rejected because you applied for a card that wasn’t built for your situation. That’s it.
Not a verdict on your character.
Not proof that you’ll never qualify. A mismatch between your current credit profile and a product designed for someone with a different one.
More than half of all credit card applicants in the U.S. have been denied at least once since 2022. You’re not the exception.
You’re in the majority and there are real options built specifically for where you are right now.
Why Most People Get Denied (And Why It’s Not What You Think)
Denials almost always come down to one of three things:
- Your score is below the card’s threshold. Most standard credit cards — the ones advertised everywhere — require a score of 660 or higher. If your score is below that, the application gets rejected automatically, regardless of your income or your intentions.
- Too many recent applications. Every time you formally apply for a credit card, the issuer runs a hard inquiry on your credit report. That temporarily lowers your score by a few points. Six or more hard inquiries in a short period signals risk to lenders — and makes the next denial more likely.
- Not enough credit history. If you haven’t had much credit activity, there’s nothing for issuers to evaluate. A thin file can be just as limiting as a negative one.
None of these are permanent. They’re the starting point and each one has a specific path out.
The Step Most People Skip Entirely
After a denial, the fear of another rejection (and another hit to your score) stops most people from trying again.
What most people don’t know is that you don’t have to formally apply to find out if you’ll get approved.
Major issuers like Capital One offer pre-qualification tools. You enter some basic information, they run a soft check (not a hard inquiry), and you see your approval odds. Your score doesn’t move. Nothing goes on your credit report.
This is the step that changes the equation. You’re not risking another rejection. You’re just getting information before you commit to anything.
What to Look for in a Card When You’ve Been Denied Before
Not all cards are built the same. For someone rebuilding or starting with damaged credit, the right card has a few specific characteristics:
- Low or no annual fee. You shouldn’t be paying just for the privilege of having the card.
- Reports to all three credit bureaus. Equifax, Experian, and TransUnion. If a card only reports to one or two, you’re building a partial record. That slows everything down.
- A clear upgrade path. The best rebuilding cards have a documented path to a better product, higher limit, no deposit, cash back rewards once you’ve established your payment history.
- Accessible approval. Designed for scores in the 500-620 range, not the 700+ range.
A Card Built for This Exact Situation
The Capital One Platinum Secured is one of the more accessible options for people with limited or damaged credit history.
What makes it different from most secured cards:
No annual fee. Most cards for bad credit charge $39–$99 just to keep the account open. The Capital One Platinum Secured charges nothing.
A deposit that can start low. Instead of a flat $200, Capital One sets your refundable security deposit at $49, $99 or $200 depending on your credit profile. Any of those tiers opens a credit line of at least $200.
It reports to all three bureaus. Every on-time payment builds your record across Equifax, Experian, and TransUnion simultaneously.
A path to an unsecured card. Capital One reviews your account over time for a higher credit line and for an upgrade to an unsecured card, and your deposit is refunded when you upgrade or close the account in good standing.
How the deposit works:
The card requires a refundable security deposit, which sets your credit limit. You can also add more deposit to raise your limit, within the terms Capital One shows you when you apply. Check the exact tier and terms in the pre-qualification step before you commit.
Who this card is for:
- People with scores between 500 and 620
- Anyone with a limited or damaged credit history
- People who want a low-cost rebuilding tool with no annual fee
- Anyone who can front a deposit of $49 or more
Who should look at other options:
If you can’t front even $49 right now, the Self Credit Builder + Secured Visa lets you build the deposit over time through small monthly payments before accessing the card. It takes longer, but it removes the upfront cash barrier entirely.
What Happens After You Get the Card
Getting approved is step one. What you do in the next 12 months is what actually moves the needle.
Two factors control 65% of your credit score:
- Payment history (35% of FICO): Pay your balance on time, every month. Even one missed payment sets the process back significantly.
- Credit utilization (30% of FICO): Keep your balance below 30% of your credit limit. If your limit is $200, try to keep your balance under $60. Below 10% is even better.
People who follow this consistently for 12 months typically see score increases of 50 to 100 points. That improvement opens access to unsecured cards, better loan terms, and lower interest rates across the board.
Now what?
Well, now you have two options:
1. If you’re not quite ready yet maybe you want to understand your situation a little better first, or explore what else is out there. That’s completely fine. There’s no rush, and the right move is always the informed one.
My situation is different2. If you’ve read this far and something clicked if you’re ready to stop waiting and take a real step toward changing where you stand financially then this is it. One application. No impact to your score to check. Just a clear answer on whether you qualify.
Pre-qualify for Capital One Platinum Secured