Mortgage rates climb past 7% again: essential steps for homebuyers today
Mortgage rates have climbed back over 7%. Learn the reasons behind this increase, how it impacts your payments, and the best steps for homebuyers to take today.
Mortgage rates continue to rise: what it means for homebuyers’ budgets
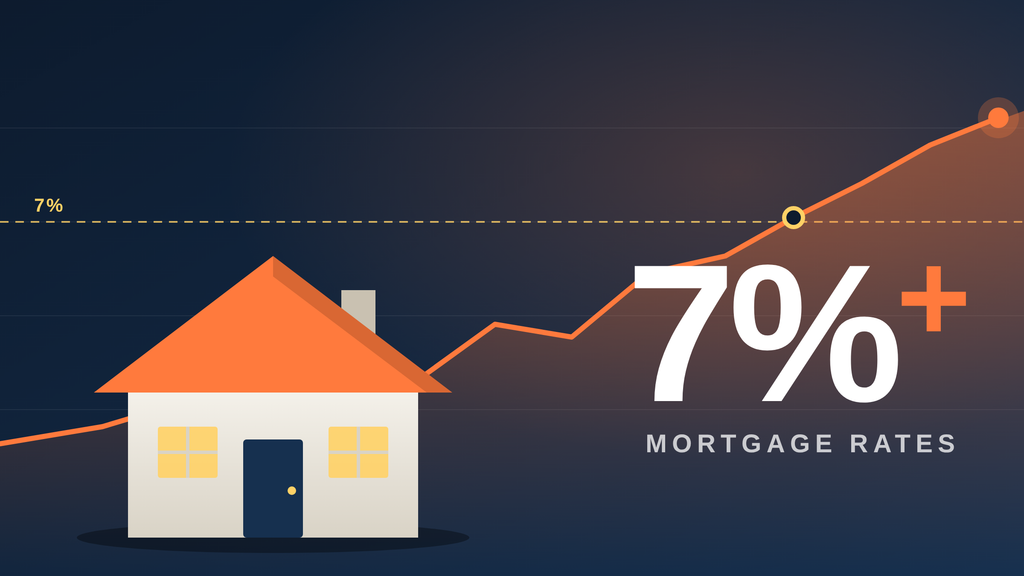
Mortgage rates are climbing once again, forcing homebuyers throughout the U.S. to face higher costs on their journey to owning a home.
In October 2026, the average 30-year fixed mortgage rate hit 7.40%, increasing borrowing expenses for families already challenged by housing affordability.
With home prices still elevated and inflation straining household finances, rising borrowing costs are pushing monthly mortgage payments out of reach for many.
Even buyers with steady incomes and strong credit scores may find their borrowing limits lower than anticipated.
Knowing the reasons behind rising mortgage rates, understanding how much more you might pay, and learning what actions to take before applying can help you steer clear of expensive mistakes.
Before submitting an offer on a home, here’s what every buyer should know and do right now.
What’s Driving Mortgage Rates Above 7% Again?
Mortgage rates have surpassed 7% once more due to rising inflation worries, shifts in the bond market, and ongoing doubts about the economic future.
Freddie Mac reports that the average rate for a 30-year fixed mortgage hit 7.40% on October 8, 2026.
It later dropped slightly to 7.24% on October 29 but stayed above the 7% mark.
This is important because mortgage rates affect the amount buyers can afford and the share of their monthly income spent on housing.
Multiple economic factors contribute to this rise.
How Inflation and Treasury Yields Impact Rates
Inflation remains a key driver behind long-term borrowing expenses.
In September 2026, the Consumer Price Index (CPI) rose by 0.6% from the previous month, while the yearly inflation rate hit 3.7%, according to data from the U.S. Bureau of Labor Statistics.
Energy costs were a key driver of this rise, with gasoline prices climbing 9.1% over the course of the month.
Rising energy expenses impact transportation, household budgets, and can shape wider inflation expectations.
If investors worry that inflation will stay high, they tend to require greater returns on their long-term investments.
A key reference point in this context is the 10-year U.S. Treasury yield.
Mortgage rates aren’t directly linked to this yield, but both are shaped by expectations around inflation, economic growth, and upcoming interest rate changes.
How the Federal Reserve’s Decision Impacts Homebuyers
The Federal Reserve’s choices in monetary policy often shape market expectations across financial sectors.
Still, these decisions don’t directly set mortgage rates.
On October 28, 2026, the Federal Open Market Committee (FOMC) chose to keep the federal funds target rate steady between 3.75% and 4.00%.
The Fed also noted that inflation levels remain high.
For homebuyers, it’s key to understand that the federal funds rate mainly impacts short-term borrowing costs.
On the other hand, 30-year mortgage rates are influenced by expectations in the long-term market.
That’s why cutting the Fed’s rate doesn’t always lead to lower mortgage costs.
Rather than depending solely on Fed announcements, buyers should keep an eye on Freddie Mac’s weekly mortgage rate updates and get fresh quotes from lenders.
The Effects of Rising Mortgage Rates on Homebuyers
An increase in mortgage rates might seem minor when viewed as a simple percentage change.
Yet, over the span of a 30-year loan, even a single percentage point difference can greatly affect the total amount paid by the borrower.
This impact is particularly significant for those borrowing larger sums to purchase a home.
Why It’s Becoming Tougher to Afford a Home
Rising borrowing expenses are just one aspect of the challenge.
In addition, home prices along with the scarcity of available listings also affect the total cost buyers face.
Data from the National Association of REALTORS® (NAR) shows the median price for existing homes was $417,500 in September 2026.
This marked a 1.3% rise compared to the same month in 2025.
Although existing-home sales grew by 1.5% from the previous month, they were still down 2.2% from the prior year.
There were about 1.60 million homes available, which equals roughly 4.8 months’ worth of supply.
This situation poses challenges for buyers relying on financing.
Even when a home’s price seems reasonable, a rise in mortgage rates can boost monthly payments enough to exceed a buyer’s budget limits.
For those buying their first home, this might result in:
- Delaying the decision to buy.
- Opting for smaller homes.
- Searching in more affordable areas.
- Building savings for a bigger down payment.
For current homeowners considering a move, rising rates can make it tougher to justify swapping out an existing mortgage for a costlier new loan.
How Homebuyers Should Respond When Mortgage Rates Rise Above 7%
Mortgage rates topping 7% doesn’t mean buyers must cancel their home purchase plans.
That said, buying a home now calls for more thorough financial planning and caution.
Instead of just looking at the quoted interest rate, buyers need to assess the overall cost of borrowing.
Consider these actionable tips before you finalize your mortgage contract.
Get Quotes From Multiple Mortgage Lenders
A key step is to gather mortgage rate quotes from various financial institutions.
Different lenders—such as banks, credit unions, and mortgage companies—may offer varying rates, fees, and loan terms even for borrowers with similar financial backgrounds.
The Consumer Financial Protection Bureau (CFPB) advises that comparing Loan Estimates helps buyers spot differences between offers and can lead to negotiating better mortgage terms.
The CFPB also states that lenders typically must deliver a Loan Estimate within three business days after receiving the six essential pieces of information needed for the application.
When selecting a lender, make sure to compare:
- Interest rate: The percentage charged on the borrowed amount.
- APR (Annual Percentage Rate): A broader measure of borrowing costs that includes the interest rate and certain loan-related charges.
- Loan term: Whether the mortgage lasts 15, 20, or 30 years.
- Closing costs: Fees required to complete the transaction.
- Discount points: Upfront payments that may reduce the interest rate.
- Monthly payment: The amount due each month, considering the costs included in the estimate.
A mortgage with a lower interest rate advertised isn’t always the best deal.
For instance, one lender might offer a reduced rate but charge higher discount points or closing fees.
Another lender might provide a slightly higher interest rate but with lower upfront fees.
The key is to evaluate the overall financial effect, not just the advertised rate.
Boost Your Credit Score Before Applying
Your credit rating plays a significant role in determining the mortgage rates and loan conditions you qualify for.
Lenders typically evaluate credit data to gauge the likelihood a borrower will repay the loan.
Having a stronger credit history can increase your likelihood of securing better loan terms.
Before submitting your application, consider following these tips:
- Verify your credit reports for any errors.
- Make payments on time and avoid late fees.
- Lower your credit card balances when you can.
- Limit opening multiple new credit lines before applying.
- Assess your current debts and monthly expenses.
It’s also key to recognize that mortgage credit score requirements vary across lenders and loan types.
Different loan options, including Conventional, FHA, and VA programs, each have their own credit criteria.
Buyers should inquire with lenders about which credit scoring models and criteria apply to the mortgage products they’re interested in.
Enhancing your credit profile might require time, but it can improve your leverage when discussing loan terms.
Think About Making a Larger Down Payment
Putting down more money upfront can lower the total loan amount you need to finance.
This often results in smaller monthly payments for principal and interest.
For instance, buying a home priced at $400,000 involves:
- 10% down payment: $40,000, leaving a $360,000 loan.
- 20% down payment: $80,000, leaving a $320,000 loan.
Reducing the loan amount can significantly impact your costs, especially when rates are over 7%.
Additionally, putting down more money could help some conventional borrowers bypass private mortgage insurance (PMI), which usually applies when the loan-to-value ratio goes beyond 80%, depending on the loan details and program rules.
Still, contributing a larger down payment isn’t always the ideal choice.
Buyers should resist the urge to deplete all their savings in order to lower their mortgage balance.
It’s crucial to keep an emergency fund intact, especially to cover unexpected repairs, rising insurance costs, or other sudden household expenses.
A well-planned down payment should ease the mortgage burden without putting the buyer’s financial security at risk.
Understanding Rate Locks and Mortgage Points
With mortgage rates fluctuating often, buyers might want to secure an interest rate ahead of closing by locking it in.
A mortgage rate lock is a commitment that shields the borrower from rising interest rates for a set period, as long as the loan closes within the agreed timeline and there are no significant changes to the application that affect the terms.
The Consumer Financial Protection Bureau (CFPB) notes that rate locks typically last 30, 45, or 60 days, though some lenders may offer longer durations.
Before you agree to a rate lock, make sure to ask your lender:
- How long will the rate remain locked?
- Is there a fee to lock the rate?
- What happens if closing is delayed?
- Can the rate be adjusted if market rates fall?
- How much would an extension cost?
Another strategy is to buy mortgage discount points upfront.
These fees are paid upfront to the lender in return for a chance to secure a lower interest rate.
Still, the actual benefit depends on how much the rate drops and the length of time the borrower keeps the loan.
For instance, if a buyer expects to sell or refinance within a few years, they might not recoup the upfront expense of buying points.
Be sure to weigh the initial cost against the possible long-term savings before deciding to buy points.
Author’s Perspective
Mortgage rates climbing back above 7% serve as a crucial signal for prospective homebuyers in the U.S.
However, the biggest error buyers make is reacting impulsively to headlines instead of carefully assessing their own finances.
Remember, a mortgage is a long-term obligation, and the interest rate is just one factor in the overall decision.
Costs like property taxes, homeowners insurance, upkeep, HOA fees, closing expenses, and emergency funds all need careful consideration before finalizing a mortgage.
With the average 30-year fixed mortgage rate at 7.40% and the median existing-home price about $417,500, buyers are navigating a tough affordability landscape.
Here’s my advice: don’t let the fear of rising rates push you into a mortgage that stretches your budget beyond comfort.
Be sure to shop around with several lenders, review all fees carefully, and estimate your monthly housing costs before committing to an offer.
The ideal time to buy a home isn’t always when mortgage rates hit their lowest levels.
Instead, it’s when the purchase aligns with your financial situation and lets you maintain stability once you’ve moved in.
Recommended content
Why savings rates may finally climb again
Learn what the Fed’s decisions mean for your money and how to compare high-yield savings accounts.
Continue Reading * You will remain on the current website