Why your minimum payment today reduces less of your debt
Learn why making only the minimum payment shrinks your credit card debt more slowly, how interest impacts your balance, and strategies to help you clear it sooner.
Caution: your minimum payment might be keeping you stuck in debt
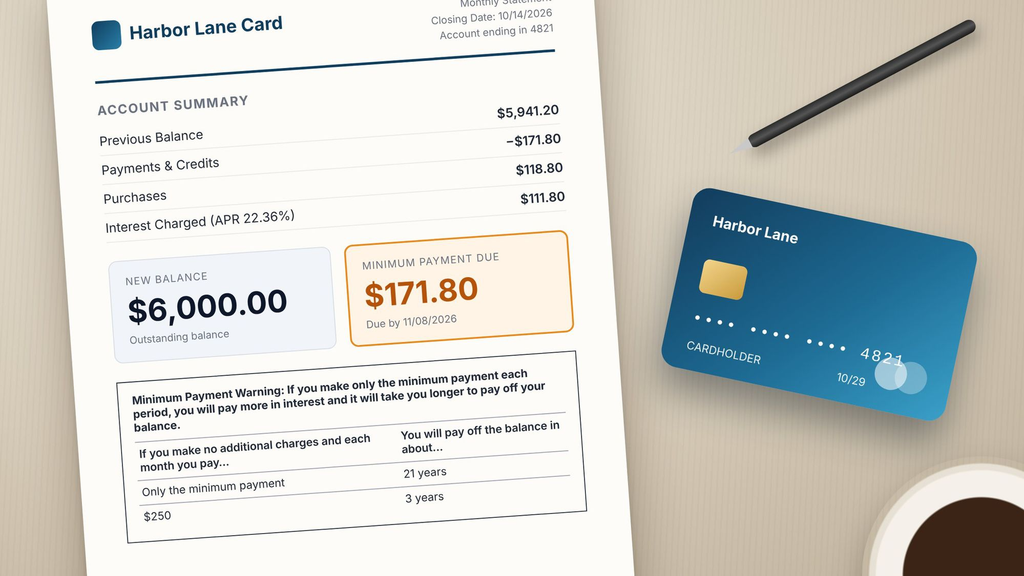
You make your credit card payment each month. So why does your outstanding balance hardly go down?
The culprit could be your minimum payment. When interest rates rise, a large portion of your payment may cover interest charges rather than lowering your principal.
Adding new charges and fees can make the situation even more challenging.
According to the Federal Reserve, in August 2026, the average annual interest rate on U.S. credit card accounts charging interest was 22.36%.
At the same time, Americans carried about $1.263 trillion in credit card debt during the second quarter of 2026.
Knowing how your minimum payment is calculated can help you lower interest charges and make meaningful strides toward paying off your debt.
Why Your Minimum Payment Pays Down Less Debt
The minimum payment is the lowest amount your credit card company requires you to pay by the due date to keep your account in good standing.
However, here’s the catch: paying only the minimum doesn’t mean you’re making much headway in reducing your debt.
The Consumer Financial Protection Bureau (CFPB) cautions that making only minimum payments usually results in higher interest charges and a longer time to clear your debt.
There are three key reasons why paying off your debt can become more difficult.
1. High Interest Rates Reduce Your Payment’s Impact
Carrying a balance on your credit card means interest charges increase the total amount you owe.
The higher your APR (annual percentage rate), the greater the interest portion of your payment.
Here’s an example to consider:
- Credit card balance: $5,000
- APR: 22.36%
- Estimated monthly interest: $93.17
- Hypothetical minimum payment: $100
- Amount reducing principal: only $6.83
This example simplifies the process; it’s not a one-size-fits-all minimum payment rule. Actual interest depends on your daily balance, billing cycle, and card terms.
The key point remains: high interest rates can leave very little of your payment to actually reduce your debt.
2. Your Minimum Payment May Vary Over Time
Credit card companies apply various methods to figure out your minimum payment.
Your minimum payment might be calculated based on a percentage of your balance, a set dollar amount, interest and fees, or a mix of these depending on your card’s terms.
When your balance drops, your minimum payment could also go down accordingly.
This might make your monthly bill feel more manageable, but sticking to just the lowered minimum might slow your debt payoff.
Tip: If you can, try to keep paying more than the minimum even as it drops to speed up reducing your balance.
3. New Purchases Can Undermine Your Progress
Just making payments doesn’t always mean your balance is shrinking quickly.
Picture this:
- Pay $200 toward your card.
- Add $150 in new purchases.
- Incur $40 in interest and fees.
Your overall balance drops by just $10, assuming no other charges or adjustments.
That’s why it’s important to monitor more than just your monthly payment. Keep an eye on your balance, interest fees, charges, and any new spending all at once.
What Can Happen If You Only Pay the Minimum?
Paying just the minimum keeps your account in good standing, but relying on it repeatedly can make your debt cost you more in the long run.
Here are three possible effects to consider.
You End Up Paying More Interest
The longer you keep a balance, the more interest charges you will build up.
Based on your APR and how you pay, interest may become a large portion of what you owe overall.
It Takes Longer to Eliminate Your Debt
When interest uses up most of your payment, the amount you owe on the principal drops very slowly.
Continuing to add new charges can make it even more difficult to pay off your debt.
Less Money Available for Your Other Financial Goals
Interest payments reduce the funds you have left for other important expenses like:
- Rent and groceries
- Emergency savings
- Retirement contributions
- Other outstanding bills
When funds are limited, making just the minimum payment might be your only practical choice for now. The key is to recognize the costs involved and aim for a repayment plan you can maintain.
Ways to Make Your Minimum Payment Pay Down More Debt
You don’t have to transform your finances all at once.
Begin by taking a few simple, manageable actions.
Whenever Possible, Pay More Than the Minimum
If your minimum payment is $100 and you can comfortably pay $150, that extra $50 will help lower your principal more quickly.
Reducing your principal balance also means you’ll pay less interest in the future.
Still, avoid pushing your budget so far that you have to borrow more just to cover basic needs.
Pick a payment amount that you can comfortably maintain every month.
Examine Your APR and Credit Card Statement
Your monthly credit card statement can reveal why your balance isn’t dropping as expected.
Look closely at these items:
- Your current APR
- The interest charged
- Your minimum payment
- Your payment due date
- Your outstanding balance
Now, consider this:
Is my balance truly going down?
Look at your balance month over month. If it barely shifts, take a closer look at your interest fees and recent charges.
Request a Lower APR From Your Card Issuer
If high interest rates are making it tough to repay, reach out to your credit card company.
Find out if you might be eligible for:
- A reduced interest rate
- A hardship assistance plan
- Alternative payment options
While approval isn’t assured, simply asking can reveal more manageable repayment choices.
You might also want to explore balance transfer cards or debt consolidation loans.
Before you accept any offer, be sure to review transfer fees, promotional period end dates, and the standard APR that applies afterward.
A lower advertised interest rate doesn’t always translate to a more affordable option.
Review Your Repayment Estimate
Credit card statements often include disclosures outlining the time and expense involved if you pay only the minimum amount.
Your statement might also provide an estimated monthly payment needed to clear your balance within 36 months.
Take a close look at that estimate and see how it fits within your budget.
If the recommended payment feels too large, pick an amount that’s manageable and adjust your plan as your financial situation evolves.
Why October Is an Ideal Time to Assess Your Credit Card Debt
October marks National Financial Planning Month across the U.S.
This month serves as a perfect prompt to evaluate your spending, current debts, and financial objectives before the year ends.
October 15, 2026, also marked the American Bankers Association Foundation’s annual Get Smart About Credit Day, a campaign dedicated to promoting credit literacy.
With the holidays and travel season coming up, some advance planning can help you steer clear of unnecessary credit card debt.
Use October as a chance to take five important steps:
- List your balances and APRs. Identify your most expensive debts;
- Review your interest charges. See how much of each payment reduces your principal;
- Set a realistic payment target. Protect your budget for essential expenses;
- Plan holiday spending. Decide what you can afford before shopping;
- Track your progress. Compare your balance every month.
You don’t need to pay off all your debt by year’s end. The aim is to wrap up the year with a clearer, more manageable plan.
When to Get Assistance With Credit Card Debt
If your balance continues to rise or you can’t keep up with your minimum payments, it’s important not to ignore the issue.
The CFPB advises reaching out to your credit card provider promptly if you’re struggling to pay your bill.
Inquire about hardship programs, lower interest rates, or alternative payment plans that might be available.
Another option is to seek help from a trustworthy nonprofit credit counseling service.
Watch out for companies that:
- Promise to erase your debt completely.
- Charge large fees upfront.
- Advise you to stop contacting your credit card provider.
These are often red flags indicating potentially unsafe debt relief offers.
If covering essentials is a challenge, focus on your basic needs first and consult trusted professionals before agreeing to any repayment plans.
Author’s Perspective
Dealing with credit card debt can be discouraging, especially when it feels like you’re doing everything right.
You consistently pay your bill each month, but your balance hardly decreases.
The issue is that your minimum payment is set to fulfill a required amount, not necessarily to help you clear your debt quickly.
Especially when rates are high, the gap between paying just the minimum and adding a bit more can make a big difference.
That said, it’s important not to cut back on vital expenses just to speed up your debt payments.
Begin by checking your APR, getting familiar with your statement, and choosing one practical change to make.
You could pay a bit more, refrain from adding new charges to a balance-carrying card, or request a lower interest rate from your issuer.
You don’t have to clear your debt all at once. It’s important to grasp why your minimum payment barely reduces your balance and develop a feasible plan to improve that.
Recommended Content
2027 social security raise
Learn when payments change, how much you may receive, and how Medicare costs affect your budget.
Continue Reading * You will remain on the current website